
AI development slowdown: what it means for Nvidia, Micron and other chip stocks
AI Sentiment: 35/100 Bearish
This score is generated through AI-driven analysis of the article's content.

powered by

Buy MU. The article flags “crowded” chip exposure getting punished on AI-development slowdown talk, but also notes no concrete evidence hyperscalers are cutting capex and that revenue targets already reflect spending plans. MU is a high-beta way to own memory demand that should stay supported by ongoing data-center buildout even if AI capability improves more slowly. Key risk: Micron’s customers actually cancel/slow memory orders (not just debate), forcing a real demand drop and margin compression.
Key Risk: Orders get cancelled and memory demand falls materially, not just sentiment.
Sell NVDA. The selloff is “punishing the picks-and-shovels layer harder,” but NVDA is still the most crowded AI infrastructure winner and trades on uninterrupted AI progress. If the market starts pricing a slower capability curve plus more regulation, NVDA’s premium multiple is the first thing to compress. Key risk: Hyperscalers keep accelerating capex and NVDA’s revenue growth stays clearly ahead of expectations, keeping the multiple intact.
Key Risk: AI capex stays on track and NVDA keeps beating growth targets, preventing multiple compression.
- Calls to slow AI development have refuelled concerns about the AI trade.
- Experts say calls to slow AI development were unlikely to derail fundraising.
- Analysts say recent developments likely to only cause short-term volatility.
Investors are beginning to question the durability of the stock market’s AI-led rally after prominent industry figures called for a slower pace of artificial intelligence development, raising concerns over whether the enormous spending boom behind the sector can continue at its current pace.
The latest debate follows increasingly dire warnings about the potential risks of advanced AI and calls from industry leaders, including Anthropic CEO Dario Amodei, for more time to manage those risks.
While the comments do not necessarily imply an immediate reduction in investment, they have introduced a new uncertainty for markets that have become heavily dependent on continued growth in AI infrastructure spending.
The S&P 500 has more than doubled since the bull market began in October 2022, with massive investments by technology companies in AI data centres benefiting chipmakers, equipment suppliers, construction companies and a broad range of other businesses.
Wall Street, however, has been increasingly alert to the possibility that the spending boom could eventually lose momentum.
AI-related capital expenditure is expected to approach $800 billion in 2026, making any meaningful slowdown potentially significant for both corporate earnings and the broader economy.
"This becomes a problem if in fact you see orders being cancelled, you see data centers, construction deals being cancelled," said Chuck Carlson, chief executive officer at Horizon Investment Services in Hammond, Indiana to Reuters.
"I need to see something concrete that, in fact, there is a slowdown versus just talk."
Chip stocks bear the brunt of AI fears
The first clear market reaction came in semiconductor stocks, which have become one of the most popular ways for investors to gain exposure to the AI boom.
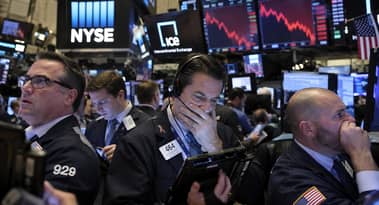
Shares of the iShares Semiconductor ETF tumbled nearly 6% on Monday as investors reacted to concerns that a slowdown in AI development could eventually translate into weaker demand for the chips and memory products powering the industry.
Major semiconductor companies including Nvidia, Micron and AMD fell between 3% and 5% on Monday.
The stocks were largely flat in premarket trading on Tuesday, while the semiconductor ETF was down more than 0.2%.
Despite the selloff, the Philadelphia SE Semiconductor Index remains up more than 55% in 2026, underscoring how far the sector has run during the AI boom.
The sharp reaction may partly reflect the crowded nature of the trade.
"Markets are punishing the picks-and-shovels layer harder than the hyperscalers because it's the layer most exposed to a slowdown in the rate of capability improvement," said Erik Kratz, chief investment officer and co-head of wealth at Arena Private Wealth in Chicago in the Reuters report.
Jake Behan, head of capital markets at ETF provider Direxion, said heavily traded areas of the market can experience particularly sharp moves when investors react to new developments.
"It's not surprising to see some air come out of them in a quick way," Behan said regarding semiconductor stocks.
"There's a lot of reasons for traders to take risk off the table," Behan said, with investors wondering if they "still want to be in a crowded chip space with this slowdown question overhanging right now."
AI spending plans remain largely intact
For now, there is little evidence in the comments provided that major technology companies are preparing to abandon their AI investment plans.
AllianceBernstein Holding LP fixed-income specialists said calls to slow artificial intelligence development were unlikely to derail fundraising and capital spending by technology companies and data-centre operators.
"These are long-term fundraising plans," said Thierry Taglione, a senior investment strategist in fixed income at the firm, referring to financing moves by hyperscalers and data-center operators, Bloomberg reported.
"It's a fair concern, but we're talking 10-year tenors and beyond," he added.
"That's not going to be derailed by news over the weekend."
AllianceBernstein still expects leading AI hyperscalers to increase nominal capital expenditure in the near term, forecasting spending of more than $1 trillion next year.
The firm does, however, expect spending to slow over the following years and eventually fade, potentially becoming a drag on overall US economic growth.
Bernstein semiconductor analyst Stacy Rasgon similarly argued that a slower pace of AI development would not necessarily translate into an immediate reduction in infrastructure spending.
"Recent AI revenue targets from our companies should already be representative of spending plans, and we would be very surprised to see those plans changing materially," he said in a MarketWatch report.
Rasgon also argued that even if companies reduce the pace of AI training and advancement, that does not automatically mean spending will decline.
Regulation becomes another risk for investors
The debate is also expanding beyond the question of corporate spending to the possibility of increased government regulation.
Investors are now weighing whether attempts to impose safeguards on AI development could affect the companies that have benefited most from the infrastructure boom.
The regulatory debate comes despite President Donald Trump's comments on Monday dismissing AI safety threats as a "hoax" and downplaying the need for regulation.
For investors, the uncertainty lies in how any future rules might affect the pace of AI development, chip demand and the economics of building increasingly expensive data centres.
Semiconductor and memory companies could be among the first areas to feel the impact if regulation ultimately slows the development or deployment of advanced AI systems.
But some investors believe regulation and guardrails could ultimately strengthen the industry by making the technology more sustainable and addressing risks that could otherwise undermine adoption.
Debt could make the next phase more volatile
The bigger concern for investors may be that the AI trade is entering a different phase.
The initial wave of AI investment was supported heavily by corporate cash flows and the expectation of enormous future demand.
As the infrastructure buildout becomes larger, however, companies and data-centre operators are increasingly relying on debt and long-term financing to fund their expansion.
That could make the sector more sensitive to interest rates and broader economic conditions.
Beyond the regulatory debate, investors should therefore watch whether the economics of AI infrastructure can justify the enormous capital being committed to it.
Charles Rinehart, chief investment officer of Johnson Investment Counsel, said volatility was increasing as the AI trade moved toward a model that relies more heavily on debt rather than free cash flow, according to MarketWatch.
That means macroeconomic pressures such as higher interest rates could become a more important factor in determining the long-term success of the AI trade.
Rinehart also warned that the AI boom has altered the structure of the stock market itself.
Investors who rely on ETFs and passive strategies for diversification may have greater exposure to AI infrastructure and megacap technology stocks than they realise because of the growing concentration of major indexes.
"More equal-weight approaches or active management might be better complements for investors looking for diversification," Rinehart said.
How would the weakness impact chipmakers?
Nancy Tengler, CEO and chief investment officer of Laffer Tengler Investments, sees the recent weakness as "more likely to be a hiccup" than the end of the AI trade, according to MarketWatch.
"The AI genie is out of the bottle," Tengler wrote in a Monday note, pointing to AI adoption across industries outside technology and the productivity improvements it could generate.
Tengler acknowledged that chipmakers and memory providers could initially lose from increased regulation, but argued that investors are still assessing the implications of a potential slowdown.
She believes investors should allow the short-term volatility to settle "and then step in and buy the high-quality names."
Tengler is using the weakness in AI infrastructure stocks to add to positions including Amazon, Micron and GE Vernova.
The latest volatility is a reminder for both AI optimists and skeptics that diversification across technology holdings may become increasingly important.
Rinehart said the huge investment in AI infrastructure will ultimately need to translate into broader economic gains and profits beyond the companies supplying the equipment.
"If all the spending that we're seeing on AI infrastructure is going to bear fruit and be productive, it's going to have to generate profits outside of just the manufacturers of the equipment," Rinehart said.
The immediate question is therefore not whether AI development will stop.
It is whether a slower, more regulated and increasingly debt-funded AI buildout can continue to justify the valuations and capital spending that have powered the market rally.
For now, analysts remain broadly confident that the largest AI spending programmes will continue.
But the sharp reaction in semiconductor stocks shows that investors are becoming less willing to treat uninterrupted AI expansion as a certainty.
TLT ETF slumps, inflows jump as US Treasury yields soar
FTSE 100 tumbles as oil shock sends UK borrowing costs back to 1998
Dow futures plunge 250 points: 5 things to know before Wall Street opens
US yields just hit a 19-year high: these 5 stocks could take the biggest hit

Dangote Refinery IPO is here: here’s what you need to know
No results found
Loading articles...
Failed to load articles. Please try again.