
Why Z.ai shares sank over 10% as Chinese OpenAI rival seeks another $5 billion
AI Sentiment: 28/100 Bearish
This score is generated through AI-driven analysis of the article's content.

powered by

Buy the Asian AI “picks-and-shovels” beneficiaries of continued model spending: TSMC (TSM) and ASML (ASML). The news highlights that frontier competition is capital-intensive and compute-constrained; even if Z.ai’s valuation compresses, the industry keeps ordering chips and lithography to expand capacity. Second-order effect: more training runs and inference demand drive higher utilization and longer capex cycles across the supply chain.
Key Risk: China/US export controls or demand destruction sharply reduce AI hardware orders, breaking the capex cycle.
Sell Z.ai (stock). The $5B raise at a 10% discount plus another $4B in July screams ongoing dilution to fund frontier training/inference. Even with 400% revenue growth, Macquarie is still modeling loss-making into 2030 and Jefferies flags sustainability issues: customer concentration, low switching costs, and competitive pressure. The market is repricing AI revenue multiples downward—this financing is the catalyst that keeps that pressure alive.
Key Risk: Z.ai proves durable margins quickly (clear path to sustained profitability and low churn) so dilution stops being the story.
- Z.ai shares fell as much as 10.5% amid fundraising and wider AI sell-offs.
- The $5 billion financing adds cash but puts shareholder dilution in focus.
- Revenue rose 400%, while Macquarie forecasts losses to persist into 2030.
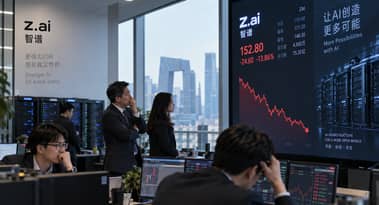
Z.ai shares sank more than 10% on Monday after the Chinese artificial-intelligence developer completed another $5 billion fundraising round, forcing investors to confront the cost of competing at the frontier.
The Beijing-based company, formerly known as Zhipu AI, raised about $2 billion through a Hong Kong share placement and roughly $3 billion through convertible bonds.
The new shares were priced at HK$714, a 10% discount to Friday’s HK$793 close.
The fall was not purely company-specific. Asian AI stocks also sold off sharply on Monday after leading industry executives called for a slower pace of model development over safety concerns.
Another $5 billion raise puts dilution back in focus
Z.ai issued 21.97 million new Hong Kong shares and sold 20.14 billion yuan of zero-coupon convertible bonds due in September 2027.
The company said proceeds will fund research and development, computing infrastructure, expansion, potential investments and acquisitions. The financing follows another $4 billion raise in July.
That makes strategic sense for a company competing with OpenAI, Anthropic and increasingly aggressive Chinese rivals. But it also highlights how capital-intensive the race has become.
Macquarie’s Ellie Jiang told the South China Morning Post that the bank is “still modelling loss-making into 2030” for Z.ai and MiniMax.
Jiang said China’s shortage of advanced compute is two to three times more acute than the global crunch, partly because US restrictions limit access to Nvidia’s most advanced processors.
Revenue is exploding, but investors are questioning its value
Z.ai’s first-half revenue jumped 400% to 953.9 million yuan, while Macquarie said annual recurring revenue had reached about $1.6 billion by August.
The bank expects ARR could approach $3 billion by year-end, above management’s roughly $2.4 billion target.
Those numbers are exceptional, but investors are becoming less willing to value every dollar of AI revenue at aggressive multiples.
Jefferies said Z.ai’s ARR guidance beat expectations but its “sustainability remains questionable”, citing customer concentration, uneven growth in computing supply, low switching costs and competitive pressure.
The brokerage maintained a Hold rating and cut its target to HK$1,183.79 from HK$1,299.80. It also reduced the multiple assigned to Z.ai’s cloud business, despite lifting revenue forecasts.
The bull case is that Z.ai is buying its way into the frontier
The fundraising can also be read as ammunition rather than distress.
Z.ai’s GLM models have moved closer to frontier performance, particularly in coding, while adoption among Chinese enterprises and overseas developers has expanded.
Goldman Sachs initiated coverage this month with a HK$1,880 target, arguing that Z.ai’s strong coding usage could sustain frequent model upgrades and reinforce its position in enterprise AI.
That creates a bullish interpretation of the latest raise: frontier-model developers that fail to secure enough compute risk falling behind permanently, making heavy spending rational while the market is still forming.
Monday’s sell-off shows investors are becoming more selective.
Z.ai may genuinely need another $5 billion to stay competitive. But shareholders also need evidence that those billions will create durable margins rather than simply higher ARR and another funding requirement.

Nikkei 225 Index outlook: Top catalysts for Japan stocks this week

Kioxia stock is stuck in a bear market: here’s why it may drop further soon

Top reasons why South Korea’s KOSPI Index is falling today (Sept. 14)

Micron, Nvidia, AMD stocks at risk as Anthropic, OpenAI leads push to slow AI growth
How will private credit and equity stocks react to Fed rate hikes?
No results found
Loading articles...
Failed to load articles. Please try again.